Are you tired of paying rent every month without owning a home? Discover how a tenancy purchase scheme in Kenya can help you move from tenant to homeowner through structured payments, subject to the terms of your agreement.
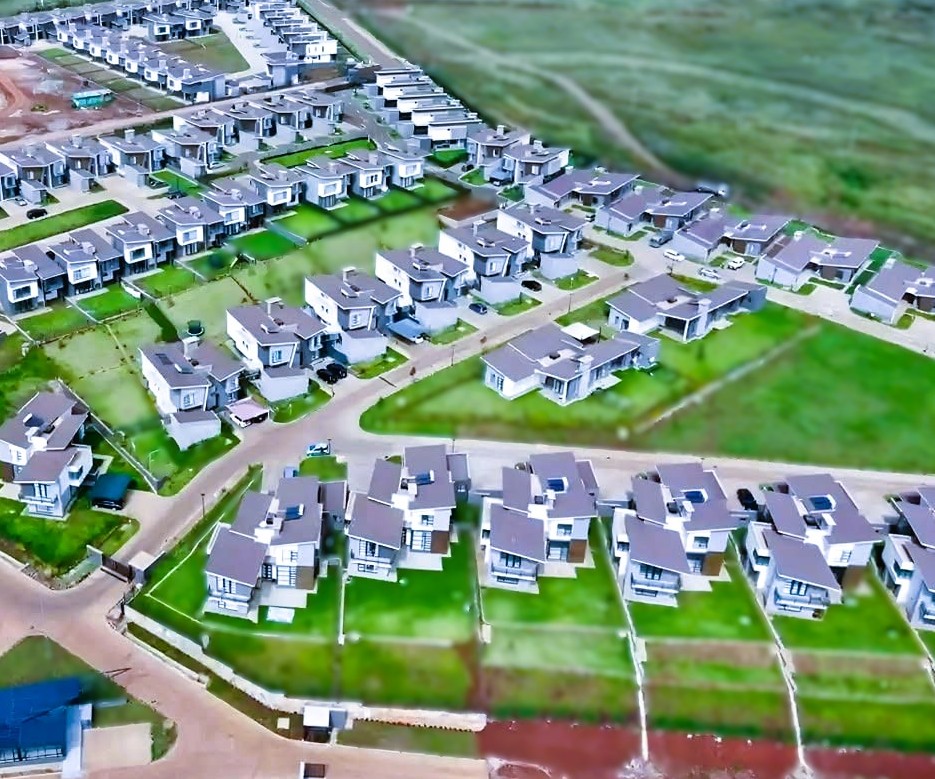
For many Kenyans, owning a house is a major life goal. However, the high cost of land, construction, and completed homes can make purchasing property outright difficult. Saving for a deposit while paying rent, covering daily expenses, and supporting a family can make homeownership feel out of reach.
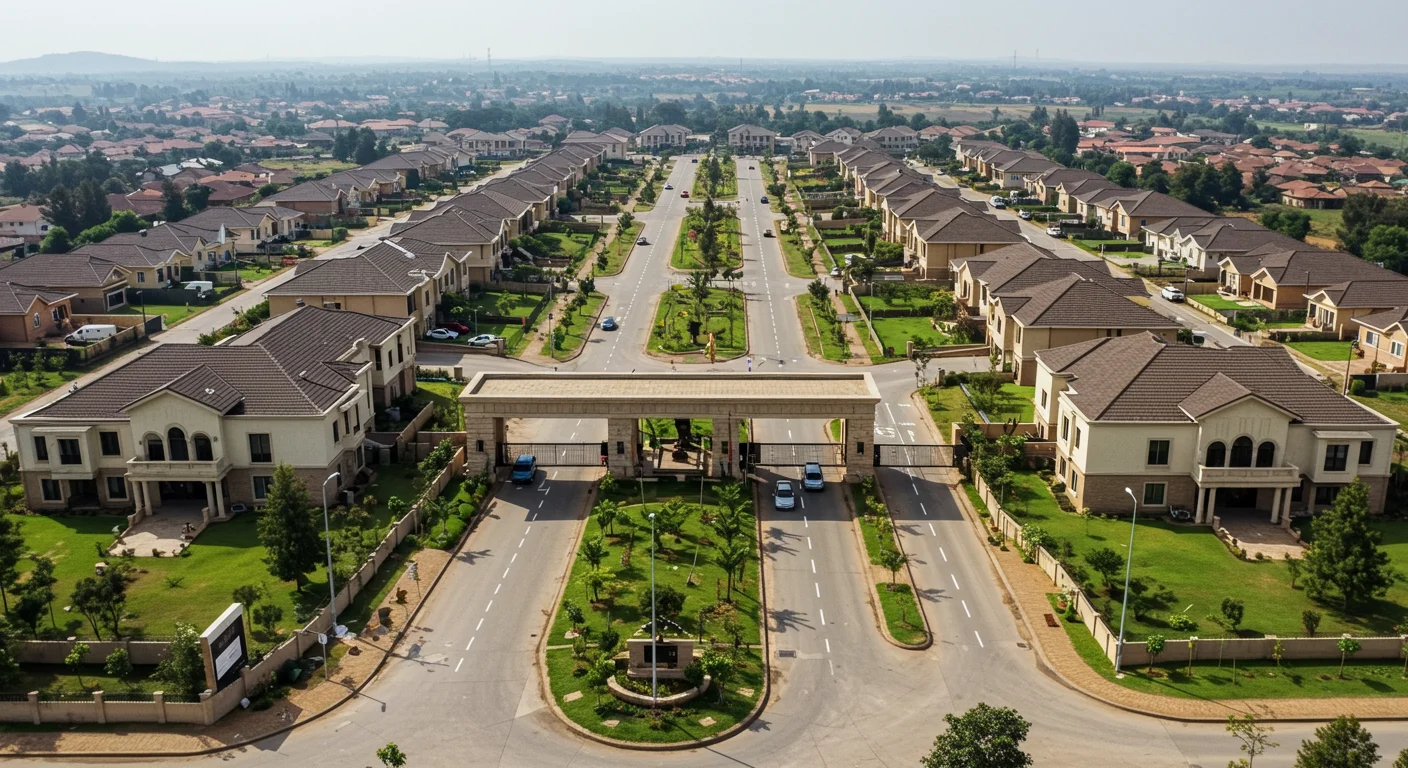
Fortunately, a tenancy purchase scheme, commonly associated with rent-to-own housing, offers an alternative route to homeownership. Depending on the arrangement, a buyer can occupy a property and make agreed payments over time, with ownership transferred after meeting the contractual requirements.
Whether you are a young professional in Nairobi, a growing family looking for a permanent home, a first-time buyer, or a Kenyan in the diaspora planning to invest back home, understanding how tenancy purchase works can help you make a more informed property decision.
In this comprehensive guide, Flama Properties explains how tenancy purchase schemes work in Kenya, their benefits, potential risks, costs, eligibility requirements, and what to consider before committing to a property.
What Is a Tenancy Purchase Scheme in Kenya?
A tenancy purchase scheme is a housing arrangement that combines occupation of a property with an agreed pathway to purchasing it. Instead of paying the full purchase price upfront, the buyer makes payments according to the terms agreed with the property owner, developer, housing provider, or other relevant party.
The precise structure varies from one scheme to another. Some arrangements allow part of the monthly payment to count toward the purchase price, while others involve separate rent and purchase instalments. Some require an initial deposit, and others specify a period within which the outstanding purchase price must be paid.
The essential point is that paying rent does not automatically mean you are buying the house. The written agreement must clearly explain whether payments contribute toward ownership, how the purchase price is settled, and when legal ownership will transfer.
In Kenya, tenancy purchase arrangements should also be distinguished from government affordable housing programmes, including any applicable tenant-purchase arrangements. Eligibility, payment structures, and ownership conditions may differ.
How Does a Tenancy Purchase Scheme Work?
Although the details depend on the provider and agreement, the process generally follows these steps.
1. Identify a Suitable Property
Start by identifying a house or apartment that meets your budget, preferred location, household needs, and long-term plans.
You may consider properties in Nairobi and its surrounding areas, including Syokimau, Athi River, Ruiru, Kiambu, Kitengela, and other locations where suitable developments are available.
Consider the property’s accessibility, nearby schools, hospitals, shopping centres, transport links, security, and potential resale or rental demand.
2. Confirm the Purchase Price and Payment Terms
Before signing an agreement, establish the total purchase price and how payments will be calculated.
Ask the property provider to clarify:
- The initial deposit or entry payment.
- The monthly rent and any additional purchase instalment.
- Whether any portion of the monthly payment is credited toward the purchase price.
- The duration of the agreement.
- Whether the purchase price is fixed or subject to adjustment.
- What happens if you miss a payment.
- When and how ownership will be transferred.
These details help you understand the true financial commitment rather than focusing only on the advertised monthly payment.
3. Sign a Written Agreement
A tenancy purchase arrangement should be documented in a clear written contract reviewed by an independent Kenyan property lawyer.
The agreement should identify the property, the parties, the purchase price, payment obligations, maintenance responsibilities, default provisions, termination conditions, and the process for transferring ownership.
It should also explain what happens to deposits and any purchase-related payments if the agreement ends before completion.
4. Occupy the Property and Make Payments
Once the contractual and handover requirements have been met, you may be allowed to move into the house and begin making the agreed payments.
Keep records of every payment, including receipts, bank transfers, and official statements from the provider. Regularly check the outstanding balance and confirm how each payment has been allocated.
5. Complete the Purchase and Transfer Ownership
When you have met the agreed financial and contractual conditions, the final purchase and transfer process can proceed.
The exact requirements depend on the property’s legal status, the agreement, and any applicable financing or housing programme rules. Confirm the necessary transfer documents, taxes, fees, and registration requirements with your lawyer before assuming that the property is legally yours.
Benefits of a Tenancy Purchase Scheme
A properly structured tenancy purchase arrangement may provide several advantages for people who want to own a home but cannot afford an outright purchase.
1. A More Manageable Route to Homeownership
Purchasing a house outright can require substantial capital. A tenancy purchase arrangement may spread the financial commitment over an agreed period, making it easier for some buyers to plan their finances.
However, affordability depends on the deposit, monthly obligations, interest or other charges, and the length of the agreement.
2. An Opportunity for First-Time Homebuyers
First-time buyers often face the challenge of raising a large deposit while managing other expenses. A suitable scheme may provide an alternative to an immediate outright purchase or a conventional mortgage.
Before committing, compare the total cost with buying the same property through other available financing options.
3. Greater Financial Planning
A clearly defined payment schedule helps buyers plan for housing costs over time.
Understanding the monthly payment, outstanding balance, additional charges, and completion date can make it easier to determine whether the arrangement fits your household budget.
4. The Possibility of Moving Into Your Intended Home Earlier
Depending on the agreement, you may be able to occupy the property before completing the full purchase price.
This can be attractive to families seeking a stable residence, provided the agreement protects their occupation rights and clearly states the conditions for continuing to live in the property.
5. A Potential Alternative to Conventional Mortgage Financing
Some tenancy purchase arrangements may offer payment structures that differ from traditional mortgages. However, they are not automatically cheaper, and they do not necessarily eliminate credit checks, deposits, financing charges, or other financial requirements.
Compare the full contractual cost before deciding which option is most suitable.
Who Can Benefit From a Tenancy Purchase Scheme in Kenya?
A tenancy purchase arrangement may suit several categories of buyers, depending on the provider’s requirements.
Young professionals: People earning a regular income who want to move from renting to owning their first home.
Growing families: Households looking for a stable residence with predictable housing costs.
First-time property buyers: Individuals who need an alternative to paying the full purchase price upfront.
Self-employed Kenyans: Business owners with demonstrable income who want to explore structured property payments.
Kenyans in the diaspora: Citizens living abroad who want to acquire a home in Kenya, subject to the provider’s eligibility requirements, payment procedures, and verification processes.
Property investors: Buyers considering a structured purchase arrangement for an eligible investment property, where the agreement permits the intended use.
Not every scheme is available to every applicant. Income verification, deposit requirements, credit assessments, residency rules, and other eligibility conditions may apply.
Tenancy Purchase Scheme vs Renting vs Buying Through a Mortgage
Understanding the differences between the available options can help you choose a realistic route to homeownership.
| Feature | Ordinary renting | Tenancy purchase | Mortgage purchase |
|---|---|---|---|
| Initial payment | Usually a deposit and rent | Depends on the agreement | Usually a deposit and associated costs |
| Monthly payments | Rent | Rent, purchase instalments, or a combination | Mortgage repayments, plus other housing costs |
| Contribution to ownership | Usually none | Only as expressly provided in the agreement | Repays the loan used to finance the purchase |
| Ownership | Landlord retains ownership | Transfers according to the contract and legal process | Buyer acquires the property subject to the applicable financing and security arrangements |
| Main consideration | Rental affordability | Contract terms and the route to ownership | Loan affordability, interest, and repayment terms |
The right choice depends on your income, savings, financial commitments, the property’s price, and the legal protections available under each arrangement.
What Are the Requirements for a Tenancy Purchase Scheme in Kenya?
There is no single set of requirements that applies to every tenancy purchase scheme in Kenya. Requirements depend on the developer, property owner, housing provider, and any applicable programme rules.
Common requirements may include:
- A valid national identity document or other accepted identification.
- A KRA PIN where required for the transaction.
- Proof of income or ability to make the agreed payments.
- Bank statements or other financial records where requested.
- An initial deposit or entry payment, if required.
- Completed application forms and successful verification.
- Acceptance of the provider’s payment schedule and contractual conditions.
Some schemes may require additional documentation or impose specific eligibility criteria.
Before paying an application fee, reservation fee, or deposit, verify the provider’s identity, confirm the property’s legal status, and obtain clear written terms.
How Much Does a Tenancy Purchase Scheme Cost in Kenya?
The cost varies according to the property, location, purchase price, deposit, payment period, financing structure, and other contractual charges.
For example, consider a hypothetical property priced at KSh 5,000,000.
If the agreed initial deposit is 10%, the calculation would be:
- Property purchase price: KSh 5,000,000.
- Initial deposit: KSh 500,000.
- Remaining purchase balance: KSh 4,500,000.
If the remaining balance were divided into 180 equal monthly payments with no interest or additional charges, the payment toward the balance would be KSh 25,000 per month.
This is an illustrative calculation, not an actual offer or a standard Kenyan tenancy purchase arrangement. It excludes rent, interest, service charges, insurance, legal costs, taxes, and other applicable expenses. Actual agreements may calculate payments very differently.
Before choosing a property, request a complete payment schedule showing the initial deposit, monthly obligations, total amount payable, additional charges, and final ownership conditions.
Important Risks to Consider Before Signing
A tenancy purchase scheme can be useful, but buyers should understand the risks before committing their savings.
Unclear Ownership Conditions
Do not assume that moving into a house or making monthly payments gives you legal ownership. Confirm the precise conditions under which ownership will transfer and what rights you have before completion.
Missed Payments and Contract Termination
Find out what happens if you lose your job, experience reduced income, or miss a payment. The agreement should explain any grace period, penalties, termination rights, and the treatment of money already paid.
Hidden Charges
Ask whether the advertised payment excludes service charges, insurance, interest, maintenance, legal fees, taxes, or other costs.
Property and Title Risks
Have an independent lawyer conduct the necessary title and ownership checks. Verify that the seller or provider has the legal authority to enter into the transaction and that the property is not subject to undisclosed restrictions or disputes.
Uncertain Transfer Timelines
Confirm when the title or other applicable ownership documentation will be transferred, which party is responsible for completing the process, and what remedies are available if the transfer is delayed.
Taking these precautions can help you make a better-informed decision and reduce the risk of unexpected financial or legal problems.
Is a Tenancy Purchase Scheme Better Than Paying Rent?
The answer depends on your financial situation and the terms offered.
Ordinary renting can be suitable if you need flexibility, are not ready to commit to a particular property, or cannot comfortably afford the long-term payment obligations.
A tenancy purchase arrangement may be more attractive if you have a stable income, understand the contract, can afford the payments, and want a defined pathway to acquiring the property.
However, do not choose a scheme simply because its monthly payment appears affordable. Compare the total cost of acquiring the home with the cost of renting and saving toward a conventional purchase.
The most suitable option is the one that supports your homeownership goals without putting your financial stability at risk.
How to Choose the Right Tenancy Purchase Property in Kenya
Before committing to a property, consider these essential factors:
- Location: Choose an area that suits your work, family, transport, and lifestyle needs.
- Affordability: Ensure that the deposit and monthly payments fit your budget after essential expenses.
- Property verification: Confirm ownership, approvals, and any relevant restrictions through the appropriate professionals and authorities.
- Contract transparency: Understand every payment obligation, termination condition, and ownership requirement.
- Long-term suitability: Consider the property’s size, accessibility, maintenance costs, and future needs.
- Professional advice: Have an independent property lawyer review the agreement before you commit or transfer substantial funds.
A home should provide security and long-term value, not become a financial burden.
Frequently Asked Questions About Tenancy Purchase in Kenya
1. Can I own a house in Kenya while paying rent?
Yes, certain tenancy purchase or rent-to-own arrangements provide a route to ownership while you make agreed payments. However, ordinary rent does not automatically count toward the purchase price. The written contract must specify how the arrangement works.
2. Is a tenancy purchase scheme the same as affordable housing?
Not necessarily. Tenancy purchase can describe different contractual arrangements, while government affordable housing programmes have their own rules, eligibility criteria, and payment structures. Check the terms of the specific scheme.
3. Do I need a deposit to join a tenancy purchase scheme?
It depends on the provider and the agreement. Some arrangements require an initial deposit, while others use different payment structures. Confirm the exact amount and whether it is refundable under specified circumstances.
4. Can self-employed people qualify?
Potentially, yes. A provider may accept evidence of business income, bank statements, tax records, or other documents to assess affordability. The requirements vary.
5. Can Kenyans living abroad participate?
Some property providers may accept eligible buyers living abroad. Applicants should verify identity requirements, payment procedures, property documentation, the authority of any appointed representative, and the arrangements for completing the purchase.
6. What happens if I cannot complete the payments?
The consequences depend on the contract and applicable law. You could face penalties, termination, or loss of some payments, depending on the circumstances and the agreement. Obtain legal advice and understand the default provisions before signing.
7. Does a tenancy purchase scheme guarantee ownership?
No. Ownership depends on fulfilling the contractual and legal requirements and completing the relevant transfer process. Verify the arrangement before making payments.
Start Your Homeownership Journey With Flama Properties
Your dream of owning a home in Kenya can begin with understanding your options and choosing a property that matches your financial ability and long-term plans.
At Flama Properties, we help prospective buyers explore property opportunities, including houses, apartments, and land for sale in Kenya. Whether you are searching for a family home, a first property, or an investment opportunity, taking time to understand the purchase terms can help you make a more confident decision.
If you are interested in exploring available properties or want to understand the purchasing options associated with a particular listing, contact our team for further information.
Contact Flama Properties
- Location: Nairobi, Kenya
- Phone: +254 715 885 476
- Email: info@flamaproperties.com
- Website: https://flamaproperties.com/